SOLUTIONS
Consulting Firm Financing
High-ticket consulting engagements often require a significant upfront investment, and even qualified clients may hesitate to commit when the full project fee is due at once. That financial hurdle can delay signed agreements, reduce deal sizes, or cause strong prospects to walk away from consulting services they are ready to move forward with.
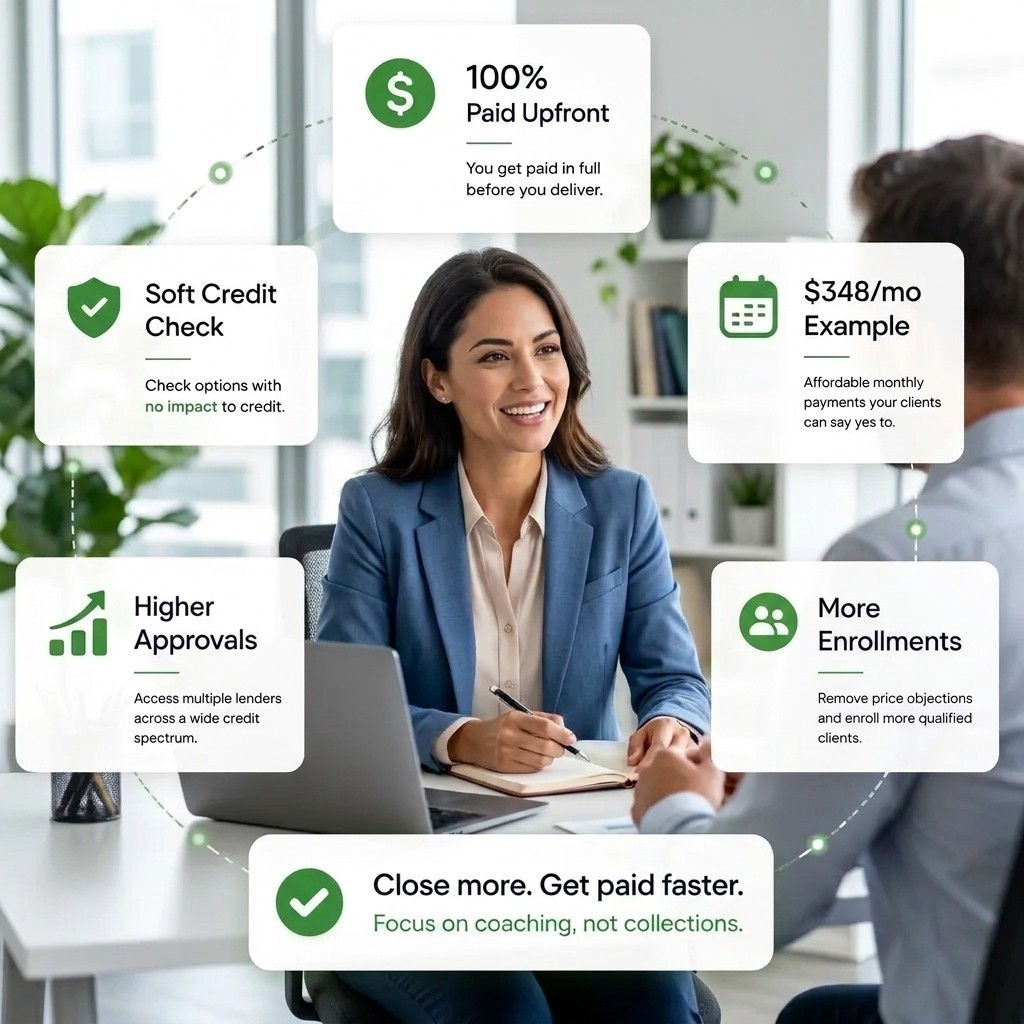
We help consulting firms overcome that barrier by giving qualified clients access to flexible financing options. Clients can spread the cost of consulting services over manageable monthly payments, while your firm receives the project fee upfront upon lender funding, without managing in-house payment plans, chasing installments, or tying up cash flow.
01
Reduce Upfront Friction
Give qualified clients a way to explore monthly payments instead of focusing only on the full upfront price.
02
Protect Pricing
Offer payment flexibility without automatically discounting your coaching program to close the enrollment.
03
Simplify Collections
Let participating lenders manage borrower repayment instead of collecting coaching installments
Consulting Firm Financing: How to Offer Flexible Payments and Get Paid Upfront
Closing a $15,000, $30,000, or $75,000 consulting engagement creates a very different payment conversation from selling a routine professional service.
A business owner or executive may understand exactly why the engagement matters and still hesitate to commit a large amount of working capital at once. The issue is not necessarily the value of the consulting work. It may simply be the timing of the expenditure.
Businesses routinely balance consulting investments against payroll, inventory, marketing, technology, hiring, taxes, and other operating priorities. Even financially healthy companies may prefer to preserve liquidity rather than make one large advisory payment upfront.
Consulting fee financing gives an eligible client another way to pay for a qualifying engagement. Instead of your firm collecting the entire balance over time, an independent financing provider may fund an approved transaction according to its program terms while the client repays the provider under a separate financing agreement.
Financing does not have to replace wire transfers, ACH, credit cards, deposits, milestone billing, or retainers. It can sit alongside those payment methods and give qualified clients another way to move forward without requiring your consulting firm to extend payment terms itself.
Which Consulting Firms Can Benefit from Offering Financing?
Financing can be particularly relevant when a consulting engagement requires a meaningful upfront investment and the client would rather preserve working capital or spread the cost over time.
Management & Strategy Consulting
Strategic planning, organizational redesign, growth advisory, succession planning, and other high-value engagements can require significant project commitments. Financing may give qualified clients an alternative to funding the entire engagement from current cash.
IT, Cloud & Digital Transformation
ERP implementation, cybersecurity work, automation, systems integration, and digital transformation can involve substantial consulting and implementation costs before the client realizes the operational benefit.
Fractional Executive Advisory
Fractional CFO, CMO, COO, CRO, and other executive advisory engagements often involve recurring commitments over several months. Financing may offer another way to structure payment for an eligible fixed engagement.
Operations & Process Consulting
Process redesign, supply-chain optimization, facility planning, workflow improvement, and operational consulting can require meaningful upfront advisory and implementation resources.
Why a Good Client May Still Prefer Financing
Asking about payment flexibility does not automatically mean a company cannot afford your consulting fee.
Businesses regularly make deliberate decisions about when and where to deploy cash. Common considerations include:
- Working Capital: The client may prefer to keep cash available for payroll, inventory, taxes, advertising, hiring, or unexpected operating expenses.
- Budget Timing: The consulting project may be approved strategically but compete with other expenses in the current quarter.
- Existing Credit Capacity: A business may prefer not to use an existing bank line, business card, or other credit facility for the engagement.
- Cash-Flow Matching: Some decision-makers simply prefer to spread a major professional-services expenditure over time.
That creates an important distinction between a client who questions the value of your proposal and one who wants the engagement but prefers a different payment structure.
Payment Timing Is Not the Same as a Price Objection
Consider two companies evaluating the same $30,000 consulting engagement:
The decision-maker is not convinced the project is worth $30,000, questions the proposed scope, or is not confident the engagement will solve the problem.
The client approves the scope and wants to begin, but prefers not to allocate the entire $30,000 from current cash during the same quarter.
Financing cannot solve Company A’s problem. Your firm still needs to demonstrate value, scope, fit, and credibility.
Company B presents a different situation. Providing another legitimate payment option may address the timing issue without changing the consulting fee itself.
Comparing Consulting Fee Payment Structures
Consulting firms use several billing methods. Each creates different implications for cash flow, administration, and client relationships.
| Billing Method | What It Means for Your Firm |
|---|---|
| Pay in Full | The client pays the agreed engagement fee upfront. Your firm receives funds without maintaining an ongoing payment schedule, while the client uses current cash or its preferred payment source. |
| Net-30 / Net-60 Invoicing | Common in B2B relationships, but your firm may deliver work and incur staffing expenses before invoices are collected. Actual payment timing can also depend on the client’s accounts-payable process. |
| Milestone Billing | Payment is connected to agreed project phases or deliverables. This can align billing with progress, but delays in approval, scope changes, or client-side dependencies may affect collection timing. |
| Third-Party Financing | An independent provider evaluates the client. If financing is approved and completed, an eligible transaction may be funded according to the provider and merchant agreements while the client repays the financing provider. |
The Operational Cost of Carrying Accounts Receivable
Allowing a consulting client to pay over time means your firm is effectively carrying part of the engagement balance while continuing to deliver the work.
Depending on your billing model, that can create several operational challenges:
- Staffing Costs: Consultants, analysts, contractors, and project managers still need to be paid regardless of when a client invoice clears.
- Administrative Work: Outstanding invoices require bookkeeping, reconciliation, reminders, and accounts-receivable follow-up.
- Client Relationship Friction: Project leaders may find themselves discussing overdue invoices while simultaneously delivering advisory work.
- Payment Risk: Organizational changes, budget freezes, disputes, or financial problems can affect the timing or collectability of outstanding invoices.
Third-party financing can reduce some of this exposure by separating the financing transaction from the consulting relationship. The exact merchant protections depend on the financing provider and the terms of the merchant agreement.
How Consulting Fee Financing Works
The financing process should remain separate from your firm’s consulting and procurement process. Your firm presents the engagement; the financing provider evaluates the application.
| Engagement Stage | What Happens |
|---|---|
Stage 1
Scope & Proposal | Present the statement of work, project scope, deliverables, responsibilities, timeline, and total consulting fee. The client should understand what they are purchasing before selecting how to pay. |
Stage 2
Payment Options | Once the client is prepared to move forward, present the available payment methods. If third-party financing is available, the client can choose whether to explore it. |
Stage 3
Financing Application | The client completes the financing provider’s secure application or prequalification process. Where offered, an initial soft credit inquiry may allow the applicant to explore potential options without affecting a personal credit score. Provider processes vary. |
Stage 4
Independent Underwriting | The financing provider evaluates the application using its own criteria. Depending on the product, this may include business revenue, time in business, personal or business credit, financial obligations, guarantor information, or other underwriting factors. |
Stage 5
Funding & Project Start | If an offer is accepted and all financing requirements are satisfied, the eligible transaction is funded according to the financing provider and merchant agreement. Your firm can then proceed with onboarding and service delivery according to the SOW. |
Where Financing Fits in the Consulting Sales Process
Financing should support an approved consulting engagement, not become the centerpiece of the sales conversation.
A practical sequence looks like this:
- Qualify the prospective client.
- Understand the operational or strategic problem.
- Define the appropriate consulting scope.
- Present the SOW, deliverables, timeline, and fee.
- Resolve questions about scope and value.
- Confirm that the client wants to proceed.
- Present the available payment methods.
- If financing is selected, direct the client to the independent provider.
- Wait for all required financing and funding steps to be completed.
- Begin the engagement according to your contract.
A useful principle: Establish the business case for the consulting engagement before discussing financing. Payment flexibility should help a qualified client execute a decision they have already made, not substitute for demonstrating the value of the project.
Merchant Fees and Recourse Terms
Some third-party financing programs charge the consulting firm a merchant fee when an eligible transaction is funded. Fees, payment timing, settlement procedures, and other requirements vary by provider and financing product.
Recourse provisions deserve particular attention because they determine which risks remain with the merchant after funding.
| Agreement Structure | What It Generally Means |
|---|---|
| Non-Recourse | The financing provider generally assumes the borrower’s repayment/default risk on an eligible funded transaction, subject to the merchant agreement and any exceptions involving refunds, disputes, misrepresentation, non-delivery, contractual breaches, or other specified circumstances. |
| Recourse | The merchant may remain financially responsible for certain unpaid amounts, defaults, chargebacks, or other obligations defined in the agreement. |
Do not evaluate a provider based on the word “non-recourse” alone. Review the complete merchant agreement and understand exactly when a funded amount can be adjusted, reversed, refunded, or charged back.
How Business and Commercial Financing Is Underwritten
Underwriting requirements vary considerably by lender, financing product, transaction size, applicant type, and whether the financing is based primarily on the business, an individual owner, or both.
Depending on the provider, underwriting may consider:
- Business revenue
- Time in business
- Business credit history
- Personal credit of owners or guarantors
- Existing debt obligations
- Cash flow or bank activity
- Identity and business verification
- Other lender-specific eligibility requirements
Your consulting firm should not predict whether a client will qualify, quote terms that have not actually been offered, or imply that your firm influences the lender’s underwriting decision.
What a Realistic Consulting Financing Scenario Looks Like
Consider a consulting firm proposing a $40,000 operational-improvement engagement:
Engagement: Six-month operations and workflow consulting project
Total consulting fee: $40,000
Payment options: Pay in full, agreed milestone payments, or eligible third-party financing
If financing is selected: The client applies directly with the financing provider and reviews any available offer
Consulting firm’s role: Deliver the engagement according to the signed SOW
Financing provider’s role: Make the credit decision and administer its financing agreement with the borrower
The important point is separation. Your firm sells and delivers consulting services. The financing provider evaluates and administers the financing.
Financing Advertising and Compliance
Businesses offering access to third-party financing should be careful about how credit terms, approval, repayment, and expected consulting outcomes are described.
The Federal Trade Commission’s advertising guidance generally requires advertising claims to be truthful and non-deceptive.
Where consumer credit is involved, the Truth in Lending Act and Regulation Z may impose additional requirements, including rules that apply when specific credit terms are advertised.
Requirements can differ depending on the financing product, whether the applicant is a consumer or business, the language used in advertising, the provider relationship, and applicable law. Follow your financing provider’s approved disclosures and obtain qualified legal advice when appropriate.
Claims Your Team Should Avoid
- “Guaranteed financing approval.”
- “Every business qualifies.”
- “No credit check” when a credit inquiry or credit evaluation may occur.
- “Our consulting work will pay off the loan.”
- “Guaranteed return on investment.”
- “You only repay the loan if the project succeeds.”
- “We are your lender” when financing actually comes from an independent third party.
A clearer approach is to explain that financing is available through independent participating providers, approval and terms are determined by those providers, and clients should review the applicable financing documents before accepting an offer.
Structuring Your SOW, Scope Changes, and Refund Process
A financed consulting engagement still needs a well-written master services agreement and statement of work.
Your documents should clearly address how the consulting relationship interacts with the financing process, particularly when a project changes or ends early:
- Scope and Deliverables: Define exactly what your firm is responsible for delivering.
- Project Milestones: Specify relevant completion points, approvals, or deliverables.
- Change Orders: Explain how additional or reduced scope affects the consulting fee.
- Termination: Explain what happens if either party ends the consulting relationship.
- Refunds: Define when refunds may be available and follow the financing provider’s procedures for financed transactions.
- Separate Agreements: Make clear that the consulting agreement and financing agreement are separate contractual relationships.
Do not assume that ending a consulting engagement automatically cancels a client’s financing obligation. Likewise, do not assume that an approved refund should be paid directly to the borrower. Follow the provider’s documented refund procedure.
Checklist: How to Evaluate a Consulting Financing Partner
Before integrating financing into your business-development process, evaluate both the client experience and your firm’s contractual obligations:
- What types of consulting engagements are eligible?
- Does the provider serve businesses, consumers, or both?
- What transaction sizes are supported?
- Which states or jurisdictions are available?
- Is soft prequalification available for applicable products?
- What happens after a client proceeds beyond prequalification?
- What underwriting information may be required?
- How are merchant fees calculated?
- When are funded transactions settled to your firm?
- What recourse provisions and exceptions apply?
- How are cancellations, disputes, and refunds handled?
- Who services the client’s financing?
- What marketing language and disclosures are approved?
- What merchant and applicant support is available?
Is Your Consulting Firm Ready to Offer Financing?
Financing works best when it is added to an already disciplined sales, contracting, and delivery process.
Before offering it, make sure your firm has:
- Clearly defined consulting services and pricing
- Written statements of work
- Defined deliverables and responsibilities
- Clear payment, termination, and refund terms
- An established change-order process
- A clear understanding of merchant fees and settlement timing
- A procedure for financed refunds and disputes
- Business-development staff trained on appropriate financing language
Frequently Asked Questions About Consulting Firm Financing
Can a consulting firm offer financing to clients?
A consulting firm can work with independent financing providers that offer eligible clients financing for qualifying engagements. The provider, rather than the consulting firm, determines whether an applicant qualifies and what terms may be available.
Does offering financing mean the consulting firm becomes a lender?
Not when the transaction is handled through an independent third-party financing provider. The consulting firm sells and delivers the professional service, while the financing provider handles its separate credit relationship with the borrower.
Can financing help a consulting firm get paid upfront?
Depending on the provider and merchant agreement, an approved and completed financed transaction may allow the consulting firm to receive the eligible project amount without collecting installments directly from the client over several months.
Is consulting financing only for clients with poor cash flow?
No. Businesses may choose financing for many reasons, including preserving working capital, managing budget timing, avoiding use of an existing credit line, or simply preferring to spread a large professional-services expenditure over time.
Does financing guarantee that a consulting project will generate a return?
No. Financing only changes how an eligible engagement is paid for. It does not guarantee business results, cost savings, revenue growth, or return on investment.
Is third-party financing better than milestone billing?
Neither model is automatically better. Milestone billing may fit firms that prefer to collect payments as work progresses. Third-party financing may be useful when a qualified client wants payment flexibility and the consulting firm prefers not to carry the balance itself.
The Bottom Line
Consulting firm financing can give qualified clients another way to fund a significant advisory engagement without requiring your firm to become their long-term payment-plan provider.
The strongest approach is to establish the business case for the engagement first. Define the problem, scope the work, explain the deliverables, present the full fee, and confirm that the client wants to proceed before discussing how they would like to pay.
If the client chooses third-party financing, keep the roles clear: your consulting firm delivers the professional services, the financing provider evaluates and administers the financing, and the client determines whether any available terms fit their circumstances.
Give Clients More Flexibility to Approve High-Value Engagements
As consulting engagements become more sophisticated and more expensive, payment timing can become an unnecessary obstacle between an approved project and a signed engagement.
Coach Financing Solutions helps consulting firms connect qualified applicants with participating financing providers while keeping credit decisions separate from the consulting relationship.
Your firm can stay focused on scoping, delivery, client outcomes, and advisory work while participating financing providers manage their own application, underwriting, and financing processes.
Want to Offer Financing for Consulting Engagements?
Talk with Coach Financing Solutions about adding third-party financing as a payment option for qualified consulting clients.
Important: Coach Financing Solutions is not a lender and does not make credit decisions. Financing is provided by participating third-party providers and is subject to eligibility, underwriting, approval, applicable terms, and provider requirements. This article is for general informational purposes only and is not legal, tax, credit, accounting, or financial advice.
Start offering flexible financing to your clients today!
Explore Financing Solutions
Explore financing solutions for high-ticket programs, consulting firms, certifications, group coaching, and masterminds.
Table of Contents
Stop losing clients over price.
Offer flexible monthly payment options that help qualified clients move forward while your coaching business gets paid upfront.