point-of-sale financing
Flight Training Financing
- Finance from $1,000 to $100,000
Give qualified clients access to flexible payment options with fast online application decisions. 2
- Get paid in full & upfront
Receive 100% of your fee upfront while lending partners handle the loan and installments.
Quick Summary
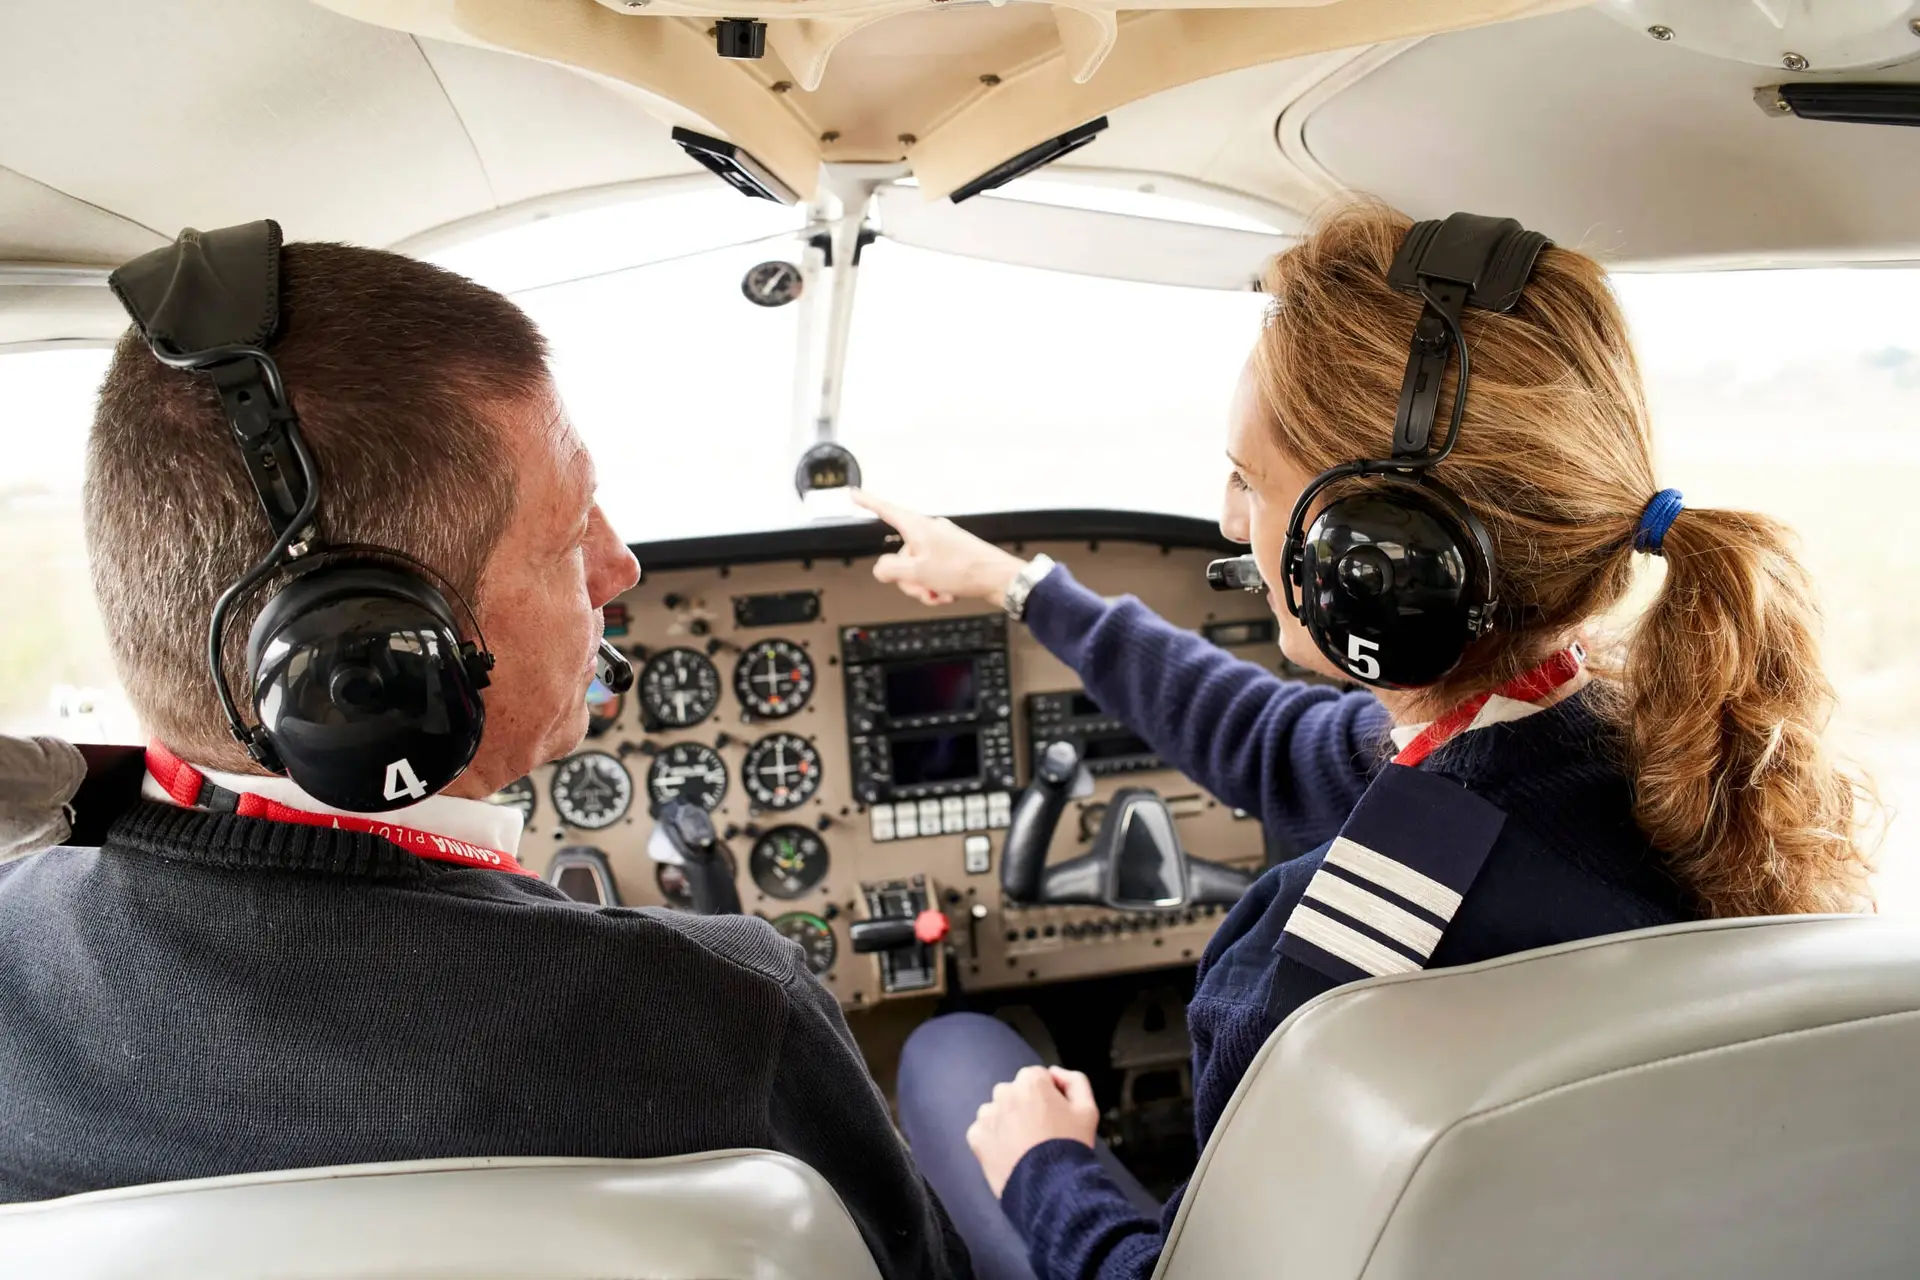
- Flight training financing helps students pay for pilot training over time. Qualified students can use third-party financing to cover eligible costs, including aircraft rental, flight instruction, and training toward FAA certificates and ratings.
- Flight schools can receive payment upfront. Once a student's loan is approved and funded, the school receives payment according to the financing agreement. The lender handles the student's loan repayments.
- Financing can help students maintain a consistent training schedule. Spreading training costs into monthly payments may make it easier for students to fly regularly rather than delaying lessons while saving money.
- Financing is available for different types of flight training. Eligible programs may include private pilot certificates, instrument ratings, commercial pilot training, and flight instructor courses. Approval, loan amounts, rates, and terms depend on the participating lender.
Flight Training Financing for Flight Schools and Student Pilots
Flight training financing gives qualified students a way to pay for eligible aircraft rental, instruction and other training costs over time through participating third-party lenders. Once financing is approved and funding requirements are met, your school receives payment according to the program agreement.
The FAA requires at least 40 flight hours for a private pilot certificate under Part 61, but many students need more. Published training estimates put a private pilot certificate at roughly $12,000 to $18,000. Adding instrument and commercial training can bring the total into the tens of thousands of dollars.
Flight school financing gives qualified students set monthly terms through a lender, so your school can offer financing for complete certificate stages, students fly on a steadier schedule, and your school receives payment while the student pays over time.
Your school receives payment when the loan funds, rather than collecting from the student after every lesson.
Financing can cover aircraft rental and instructor time, which is where most of the cost of a pilot certificate sits.
Monthly payments may make it easier for students to schedule lessons regularly.
How Flight Training Financing Works
Students who qualify can finance an eligible training program instead of paying for each lesson separately.
Students apply directly through the participating lender network and review any offers available to them. After an offer is accepted and funding requirements are met, the school receives payment under the applicable agreement. The lender handles the student’s loan repayment.
Coach Financing Solutions connects Part 61 flight schools, Part 141 pilot schools and career academies with participating financing providers, for training toward FAA certificates and ratings, from the private pilot certificate through the instrument rating, commercial certificate and flight instructor certificates.
| Stage | What Happens |
|---|---|
Step 1
Share Your Link | A student ready to start a certificate stage opens your financing link and reviews the monthly options available through participating lenders. |
Step 2
Lender Reviews and Funds | The lender applies its own criteria. Once an offer is accepted and verification is complete, funding proceeds under the program terms. |
Step 3
Schedule the First Flight | After payment is confirmed, schedule the student’s eligible training stage. |
Why Flight Schools Offer Financing
Aircraft rental and instructor time account for much of the cost of flight training. Long breaks between lessons can also mean additional practice is needed to regain proficiency. Financing may help some students maintain a more consistent schedule, although it does not guarantee faster completion or fewer flight hours.
Pilot salaries vary widely by job, experience and employer. The Bureau of Labor Statistics publishes national pay and employment data for airline and commercial pilots. Those figures provide career context, not a prediction of graduates’ earnings or employment.
- Finance flight hours, not just ground school: Aircraft rental and instruction are the bulk of the cost, and financing can cover them.
- Offer financing for a full course: Students can review the estimated cost before committing.
- Help students train consistently: Regular lessons can help students retain what they learn.
- Get paid when the loan funds: Your school does not have to collect loan payments from students.
- Offer financing for later training: Students can check their options again when they pursue another rating or certificate.
- Leave loan payments to the lender: Your staff can focus on scheduling and instruction.
- Keep your current payment options: Financing can sit alongside pay-as-you-fly, prepaid hours and VA benefits for eligible students.
Flight Training Programs That May Qualify for Financing
Financing may work best for a clearly priced certificate or rating stage. The ranges below are illustrative training estimates, not lender-approved amounts. Actual prices vary by school, aircraft, location, training pace and whether instruction follows Part 61 or Part 141.
The FAA minimum is 40 hours under 14 CFR 61.109, but most students fly 50 to 70 hours before the checkride.
Training and aeronautical experience requirements depend on the applicable FAA regulations and training pathway.
Includes time-building toward the 250 total hours required under Part 61, or 190 under Part 141.
Typically around 10 hours in a twin, where rental rates run well above single-engine aircraft.
Flight instructor and instrument instructor certificates, one possible route to gaining flight experience.
Accelerated zero-time programs to commercial and instructor certificates. ATP Flight School publishes $123,995 for its zero-time program.
Schools can discuss financing one certificate or rating stage at a time, giving students a chance to review costs and progress before taking on additional debt. Whether a particular stage is eligible depends on the lender and program.
How to Introduce Flight Training Financing to Students
Explain the estimated training cost first. Then show students their payment options, including financing if they qualify.
- Recommend the medical first: Before a student commits to financing a full stage, encourage them to get their FAA medical certificate. Many student pilots need an appropriate FAA medical certificate before solo flight, although exceptions and alternative qualification rules can apply, and finding a disqualifying issue after financing creates a problem nobody wants.
- Walk through the stage estimate: Show realistic hours, aircraft and instructor rates, materials and checkride fees, not just the FAA minimum.
- Name the payment options: Let students know a monthly option through a participating lender is available to those who qualify, alongside pay-as-you-fly and VA benefits where your school is approved.
- Share your link: Add it to your enrollment page, your discovery flight follow-up email and your training agreement packet.
- Let them review offers: The student applies directly and reviews any available lender offers.
- Confirm funding: Wait for the lender to complete verification and release funds before treating the training as paid.
- Schedule lessons: Work with the student to set a realistic training schedule.
Where to Mention Financing to Students
Show financing information wherever students look at prices or ask how to enroll:
- Discovery flight debrief: Mention monthly options while the student is still excited from their first time at the controls.
- Training cost pages: Show stage estimates with a note that monthly payment options may be available.
- Career seminars and open houses: Cover how students fund each certificate stage, including financing and VA benefits.
- Enrollment meetings: Cover the full stage estimate first, then the ways to pay.
- Training agreements: Show the monthly option beside pay-as-you-fly and block time.
- Follow-ups: When cost is the only thing holding someone back, send the link as the next step.
Flight School Financing: How It Compares to Other Options
Here is how common payment methods compare for your school:
| Payment Method | When You Get Paid | Repayment Manager | Admin Overhead | Best For |
|---|---|---|---|---|
| Coach Financing Solutions | Upfront once requirements are met | Financing provider | Low | Full certificate stages and career tracks |
| Pay As You Fly | After each lesson | Not applicable | Medium | Recreational students and occasional lessons |
| Prepaid Block Time | Upfront from the student | You hold the unused balance | Medium | Students with cash who want a block discount |
| Open Training Accounts | After hours are flown, if paid | You | High | Arrangements you bill and collect yourself |
| GI Bill (Post-9/11) | Through VA, per school certification | VA | High | Eligible veterans at VA-approved Part 141 or 142 schools |
Open Student Accounts vs. Third-Party Financing
Consider a student enrolled in a $12,000 instrument-rating program who pays for lessons through an open account. If the student falls behind, the school may have to collect the unpaid balance after the aircraft and instructor time have already been used.
With third-party financing, an approved student can pay for an eligible training stage through a lender. Once funding conditions are satisfied, the school receives payment under its agreement, and the lender handles loan repayment.
Figures are illustrative. Actual approval, loan amounts, rates, terms, and payments are determined by the participating lender.
Keep Students Flying, Not Waiting on Funds
Let qualified students pay monthly for eligible training while your school receives payment when the loan funds.
Offer Monthly Payment OptionsWhat Happens After a Student Applies for Financing
The student completes the review directly with the lender. Available offers, approval requirements, rates, fees and repayment terms are all set independently by the provider, not by your school.
Underwriting varies. Depending on the provider, a lender may look at credit history, income, existing obligations and identity verification, and some allow a co-borrower. Some providers let an applicant preview options with a soft credit check that doesn’t affect their score.
Once financing and funding are complete, you’re paid according to the agreement. Follow any funding and onboarding steps the provider asks for before the student begins the financed stage.
Weather Delays, Medical Issues and Refunds
Staying Compliant When You Offer Flight Training Financing
Aviation training draws students who are making a career decision, so how you describe outcomes matters. Pilot pay and hiring data from the BLS or the airlines is fine to share as context, but don’t promise airline jobs, hiring timelines or starting salaries. Describe your school’s FAA certification accurately, whether you train under Part 61, Part 141 or both, and be precise about VA benefits. The VA’s flight training rules require a Part 141 pilot school or Part 142 training center with an approved program, so a Part 61-only school shouldn’t imply GI Bill eligibility.
The same care applies to testimonials and graduate outcomes. Claims should be truthful, typical and backed by evidence. The FTC offers clear guidance on endorsements, reviews and testimonials.
- State the full stage estimate before discussing financing.
- Present financing as an optional, third-party payment method.
- Recommend students obtain their FAA medical before financing.
- Describe your Part 61 or Part 141 status and VA approval accurately.
- Send rate, APR and fee questions to the lender.
- Keep records of hours flown, stage checks and endorsements.
- Don’t promise airline jobs, hiring timelines or salaries.
- Don’t call private financing financial aid.
- Don’t suggest approval or funding is guaranteed.
- Don’t quote rates or fees the provider hasn’t confirmed.
- Don’t complete a student’s financing application for them.
- Don’t pressure a student to finance a full career track at once.
Is Flight Training Financing Right for Your School?
Financing may be more useful for complete certificates and ratings than for individual discovery flights or occasional refresher lessons. It gives qualified students another way to evaluate the cost of a private pilot, instrument or commercial training stage.
It works across Part 61 flight schools, Part 141 pilot schools, flight training at FBOs and accelerated career academies. For other certification programs we serve, see vocational training financing and certification program financing. If you’re weighing financing against running your own payment arrangements, our guide to payment plans vs client financing walks through the trade-offs.
Types of Flight Schools and Training Providers
Schools can offer financing for eligible programs such as:
Flexible, instructor-led training toward private, instrument and commercial certificates on the student’s schedule.
FAA-approved structured curricula with stage checks and reduced hour minimums for some certificates.
Accelerated zero-time programs that move students from first lesson to instructor certificates.
Rotorcraft private and commercial training, where aircraft hourly rates run well above trainer airplanes.
Add-on ratings that pilots need for commercial and airline careers.
CFI, CFII and MEI training, one path to gaining experience as a working pilot.
Get Started with Flight Training Financing
Coach Financing Solutions connects training providers with participating third-party financing companies. Flight schools can offer eligible students a monthly payment option for qualifying training costs without managing the loan themselves. Approval, funding and payment arrangements depend on the provider and program.
Ready to Offer Financing for Flight Training?
Talk with Coach Financing Solutions about adding third-party financing as a payment option for qualified student pilots.
Important: Coach Financing Solutions is not a lender and does not make credit decisions. Financing is provided by participating third-party providers and is subject to eligibility, underwriting, approval, applicable terms, and provider requirements. Financing is not financial aid. Cost ranges are published estimates and vary by school, aircraft and region. Pilot pay and job data are labor market statistics, not a promise of employment or earnings. This article is for general informational purposes and is not legal, tax, credit, or financial advice.
Start offering flexible financing to your clients today!
Explore Vocational Training Financing
Explore financing solutions for vocational schools, certification programs, training academies, and career-focused education providers.
Table of Contents
Stop Losing Clients Over Price.
Offer flexible monthly payment options that help qualified clients move forward while your coaching business gets paid upfront.
Illustrative monthly payment
Illustration uses a 60-month term and an example rate. Actual offers, rates, terms, and payments vary by applicant and lender.
This calculator provides estimates for illustrative purposes only and does not constitute an offer of credit or a commitment to lend. Final rates and terms depend on applicant credit profile and lender criteria.
Powered by: Coach Financing Solutions
COACH FINANCING CALCULATOR
Show clients a different way to think about your program's price.
Offer coach financing to your clients.
Scale your high-ticket enrollments seamlessly. Let third-party lenders handle the underwriting and risk while you focus on coaching.
with multiple lending partners
direct to your bank account
(Prime, Near-Prime & Subprime)
amounts from $1,000 up to $50,000+
invoicing, or default risk
Start Offering Financing Today.
Help qualified clients compare payment options in minutes to complete enrollment faster.
- Turn hesitant prospects into committed clients.
- Flexible monthly payment options for your programs.
- Get paid upfront without carrying client payment default risk.