point-of-sale financing
Financing for Birth & Family Training Centers
- Finance from $1,000 to $100,000
Give qualified clients access to flexible payment options with fast online application decisions. 2
- Get paid in full & upfront
Receive 100% of your fee upfront while lending partners handle the loan and installments.
Quick Summary
- Help Students Start Their New Career Sooner: Many aspiring doulas, childbirth educators, lactation professionals, and newborn care specialists are career changers or parents returning to the workforce. Monthly payment options can reduce the upfront tuition hurdle that delays enrollment.
- Make Multi-Certification Tracks Easier to Enroll In: Students often combine birth doula, postpartum, lactation, childbirth education, and newborn care training. Financing can make it easier to enroll in a complete certification track rather than paying for one course at a time.
- Increase Enrollment in Higher-Value Program Bundles: Bundled certification tracks can reach $2,500–$6,000, giving academies an opportunity to offer comprehensive training paths while students spread the cost over time.
- Receive Full Tuition Upfront: Once financing requirements are completed and funding clears, your academy receives tuition upfront while the student repays the lender over time.
Financing for Birth and Family Certifications: How to Offer Payment Options and Get Paid Upfront
Birth and family certification financing lets students spread tuition into monthly payments while your academy preserves its pricing and receives tuition upfront once funding clears.
Many people pursuing careers in doula care, childbirth education, lactation support, and other family-focused services are entering a new professional chapter. They may be parents returning to the workforce, career changers, or recent graduates ready to turn a strong interest in supporting families into a viable career. Professional certification gives them the training and credentials to move forward, but a large upfront tuition payment can become the final barrier to enrollment.
Financing gives qualified students access to a third-party lender network, where they can explore monthly payment options while your training program receives full tuition upfront once funding is completed.
Get Paid Upfront and in Full
Tuition lands directly in your account once funding clears, keeping receivables off your balance sheet.
Give Students a Path to Start Now
Prospective practitioners who lack immediate cash can begin the cohort today instead of delaying for months to save.
Lender Handles Repayment
Ongoing servicing belongs entirely to the lender, allowing you to mentor students rather than manage billing cycles.
What Is Birth and Family Certification Financing?
Financing lets qualifying students to spread tuition into manageable monthly installments rather than paying the entire fee upon registration. Applicants apply via a secure lending network, review the payment terms they qualify for, and finalize their selection. Once funding clears, your academy receives full tuition, and the student’s ongoing payment schedule is handled directly by the lender.
Individually, standalone credentials remain accessible. Birth doula training commonly ranges from $550 to $1,500; postpartum and childbirth educator programs sit in a comparable tier; and specialized newborn care coursework runs from $1,000 to $3,000. Hesitation arises when students realize that building a competitive, full-time practice requires multiple certifications.
How Financing Makes Multiple Certifications More Accessible
Most educators see this bottleneck firsthand: a single credential rarely supports a comprehensive, full-time income. To attract clients and command higher retainer fees, practitioners routinely package complimentary skill sets – pairing birth doula support with postpartum care, childbirth education, or specialized lactation guidance. When self-funding class by class, assembling this toolkit takes years, significantly delaying when they can launch their practice.
Financing allows candidates to package their entire curriculum into one predictable monthly plan rather than piecing it together course by course. This benefits the student while significantly increasing your multi-program enrollments, empowering committed students to sign up for complete tracks today rather than postponing their education.
How Does Financing Work for Birth and Family Certifications?
The enrollment path is simple. You provide a financing link, the lender evaluates the application and manages the repayment structure, and your academy receives tuition upfront once funding clears. The integration runs smoothly alongside your current admissions workflow.
| Stage | What Happens |
|---|---|
Step 1 Apply | The student submits a simple application through your custom portal and explores monthly payment terms available via the lending network. |
Step 2 Choose an Offer | The student selects the plan structure, duration, and monthly payment that best matches their household budget. |
Step 3 Enroll | Once funding requirements clear, your program receives full payment upfront, and the student immediately begins their coursework. |
Financing vs. Running Your Own In-House Payment Plan
Offering informal in-house installment plans may feel supportive, but carrying uncollected receivables places substantial financial and administrative strain on a training academy. Managing payment reminders and dealing with missed installments can quickly disrupt cash flow and strain educator-student relationships.
Point-of-sale financing transfers that operational burden to professional lenders. Full tuition is delivered directly to your program when funding clears, default risk is assumed by the financing provider, and you maintain a supportive mentoring focus without managing collections.
- Reliable upfront funding: Collect full tuition upon enrollment rather than chasing installments over months.
- Zero balance-sheet default risk: The lender assumes borrower repayment responsibility, insulating your business.
- Higher bundled enrollments: Enables students to purchase comprehensive multi-certification tracks at once.
- Protected price integrity: Expand accessibility through flexible financing without discounting your training value.
- Stronger student rapport: Keep the learning experience positive and educational, completely free of collections friction.
Which Birth and Family Certifications Can Be Financed?
Both standalone courses and bundled tracks are eligible for financing, with bundled programs often yielding the highest conversion lift. Common qualifying curricula include:
Birth Doula Certification
$550 – $1,500
Core training and certification for emotional, physical, and informational labor support.
Postpartum Doula Training
$600 – $1,800
Instruction on supporting parental recovery, infant soothing, and family transition during the fourth trimester.
Childbirth Educator Certification
$500 – $1,500
Curriculum development and instructional training for leading prenatal classes for expectant parents.
Lactation & Feeding Support
$1,000 – $4,000
Counselor pathways delivering foundational and advanced infant feeding support competencies.
Newborn Care Specialist
$1,000 – $3,000
Comprehensive training in specialized overnight infant care, circadian rhythms, and routine establishment.
Bundled Certification Tracks
$2,500 – $6,000
Combined multi-discipline suites providing full-spectrum professional credentials in a unified enrollment.
How to Present Payment Options During Enrollment
Position monthly financing as a standard enrollment pathway rather than a reactive concession when an applicant hesitates. Integrating payment flexibility directly into your admissions discussion helps candidates plan responsibly without feeling self-conscious about upfront costs.
- Highlight the practical outcome: Focus on the clinical and non-clinical competencies, mentorship, and career pathway before introducing tuition details.
- Present tuition transparently: Quote your total program cost plainly, immediately paired with available installment breakdowns.
- Contextualize program bundles: Frame complete tracks around modest monthly payments rather than an intimidating single investment.
- Provide your financing link: Share application access via email, direct message, or on your admissions portal so applicants can review terms with zero pressure.
- Finalize enrollment: As soon as financing completes and funding clears, welcome the student into their active cohort.
Where to Position Financing Across Your Admissions Funnel
Introduce flexible payment visibility early while prospective students are actively weighing possibilities. When high aggregate tuition is the only visible figure, many promising practitioners disqualify themselves prematurely before ever initiating contact.
Pre-Admissions Touchpoints
- Course catalog & syllabus pages: State clearly that monthly financing plans are accessible for qualified students.
- Curriculum bundle pages: Place monthly payment estimates directly alongside aggregate package pricing.
- Workshops & info sessions: Highlight payment flexibility during Q&A sessions and program overviews.
Direct Admissions Discussions
- Admissions calls: Present core training value first, followed immediately by financing and payment options.
- Bundle consultations: Leverage low monthly payments to help single-course applicants step into full certification suites.
- Follow-up sequences: If an engaged applicant cites upfront cost as their primary roadblock, offer the financing portal link as a logical next step.
How Certification Training Payment Options Compare
Here is how standard payment structures compare for certification providers:
| Payment Method | When You Get Paid | Who Manages Repayment | Admin Overhead | Best For |
|---|---|---|---|---|
| Coach Financing Solutions | Upfront once funding requirements are completed | Third-party financing provider | Low | Bundled certification tracks |
| Pay in Full | Immediately upon checkout | Not applicable | Low | Students with dedicated upfront capital |
| Credit Card | Standard merchant settlement | Card issuer and student | Low | Students leveraging existing credit lines |
| In-House Payment Plan | Incrementally over course duration | Your Academy | High | Short, manual arrangements you self-insure |
Consider a comprehensive $3,000 bundle combining birth doula, postpartum support, and newborn care certification. Self-financing that total requires monitoring multiple recurring debits and risking missed payments during active training. Point-of-sale financing provides the student with comfortable monthly terms, issues full tuition to your program once funding clears, and delegates all repayment handling to the provider. Rates, terms, approval, and available options are determined exclusively by participating lenders.
Figures are illustrative. Actual approval, loan amounts, rates, terms, and payments are determined by the participating lender.
Ready to Offer Payment Options?
Give students an accessible route into professional birth work while preserving full tuition pricing and receiving payment upfront.
What Happens After a Student Applies for Financing?
The lending partner handles the evaluation, reviewing the submission and generating customized term options. Applicants supply standard identity, income, and background details as needed. All credit determinations, interest rates, and loan structures remain strictly within the lender’s purview. Many partner lenders offer pre-qualification via a soft credit pull that does not impact the student’s credit score.
Most funding structures operate as fixed-installment loans with defined payment schedules. When funding clears, tuition settles into your program account based on your setup criteria, and you simply confirm enrollment details before classes begin.
Withdrawals, Pauses, and Refunds
Once funded, loan repayment remains strictly between the student and the lending entity, highlighting the importance of a clear enrollment agreement and meticulous documentation. Life adjustments happen frequently in adult education, making proactive institutional policies vital.
If a student misses a payment
Repayment default is managed directly by the lender. Your team simply follows standard provider protocols and maintains active proof of enrollment and curriculum delivery.
If a student pauses or defers
Clearly delineate cohort deferral and pause policies in your student enrollment contract. Pausing coursework does not modify or suspend third-party loan obligations.
If a refund is owed
Maintain explicit refund criteria prior to matriculation. Any processed refund or financing balance adjustment adheres to your written terms and platform merchant rules.
Essential Compliance Best Practices
Maintain accurate professional boundaries across your marketing copy. Doula companionship and childbirth education represent non-clinical emotional and educational support, whereas lactation consulting and specialized infant care involve more technical protocols. Transparently articulate what each credential qualifies a graduate to perform, and never characterize private certifications as clinical medical licensure.
Maintain transparent financial communication as well. Professional birth practices develop over time through dedicated networking, so avoid unrealistic earnings projections. Never present commercial point-of-sale financing as federal student aid or imply automatic credit approvals. Direct specific inquiries regarding interest rates and credit criteria to the lender.
Best Practices
- Display full tuition clearly and present financing as a convenient alternative.
- Clearly specify the non-clinical or technical scope of each credential.
- Maintain realistic, responsible career and earnings expectations.
- Incorporate compliant financing disclosures provided by your platform partner.
- Refer specific rate, fee, and credit qualification questions directly to the lending partner.
Practices to Avoid
- Do not represent non-clinical roles as medical practice or clinical care.
- Do not guarantee income benchmarks, client volume, or third-party Medicaid approval.
- Do not misrepresent commercial point-of-sale financing as Title IV or federal financial aid.
- Do not promise unconditional loan approval.
- Do not advertise specific APRs, rates, or terms unless explicitly approved by the participating lender.
Is Financing Right for Your Certification Academy?
If your training business repeatedly encounters high-intent candidates who withdraw solely due to lump-sum tuition constraints, introducing structured monthly financing is often the single most effective enrollment lever. Its impact is especially notable for bundled programs, where the total investment required to build a well-rounded practice creates an initial hurdle.
Whether certifying birth doulas, postpartum specialists, childbirth educators, lactation counselors, or newborn care professionals, flexible financing removes initial friction, preserves your tuition pricing, and provides complete upfront funding.
How to Add Payment Options to Your Enrollment Process
Coach Financing Solutions empowers birth and family certification programs to embed seamless monthly payment solutions directly into their existing admissions pipeline. Students gain a manageable way to invest in their education, your tuition pricing stays intact, and disbursements arrive upfront once funding requirements clear.
Related Financing Solutions
Ready to Add Financing to Your Certification Program?
Request partner information to learn more about adding payment options to your enrollment process.
Important: Coach Financing Solutions is not a lender and does not make credit decisions. Financing is provided by participating third-party providers and is subject to eligibility, underwriting, approval, applicable terms, and provider requirements. Certification programs do not license clinical care on their own and do not guarantee income, clients, or reimbursement. This article is provided for general informational purposes only.
Start offering flexible financing to your clients today!
Explore Vocational Training Financing
Explore financing solutions for vocational schools, certification programs, training academies, and career-focused education providers.
Table of Contents
Stop Losing Clients Over Price.
Offer flexible monthly payment options that help qualified clients move forward while your coaching business gets paid upfront.
Illustrative monthly payment
Illustration uses a 60-month term and an example rate. Actual offers, rates, terms, and payments vary by applicant and lender.
This calculator provides estimates for illustrative purposes only and does not constitute an offer of credit or a commitment to lend. Final rates and terms depend on applicant credit profile and lender criteria.
Powered by: Coach Financing Solutions
COACH FINANCING CALCULATOR
Show clients a different way to think about your program's price.
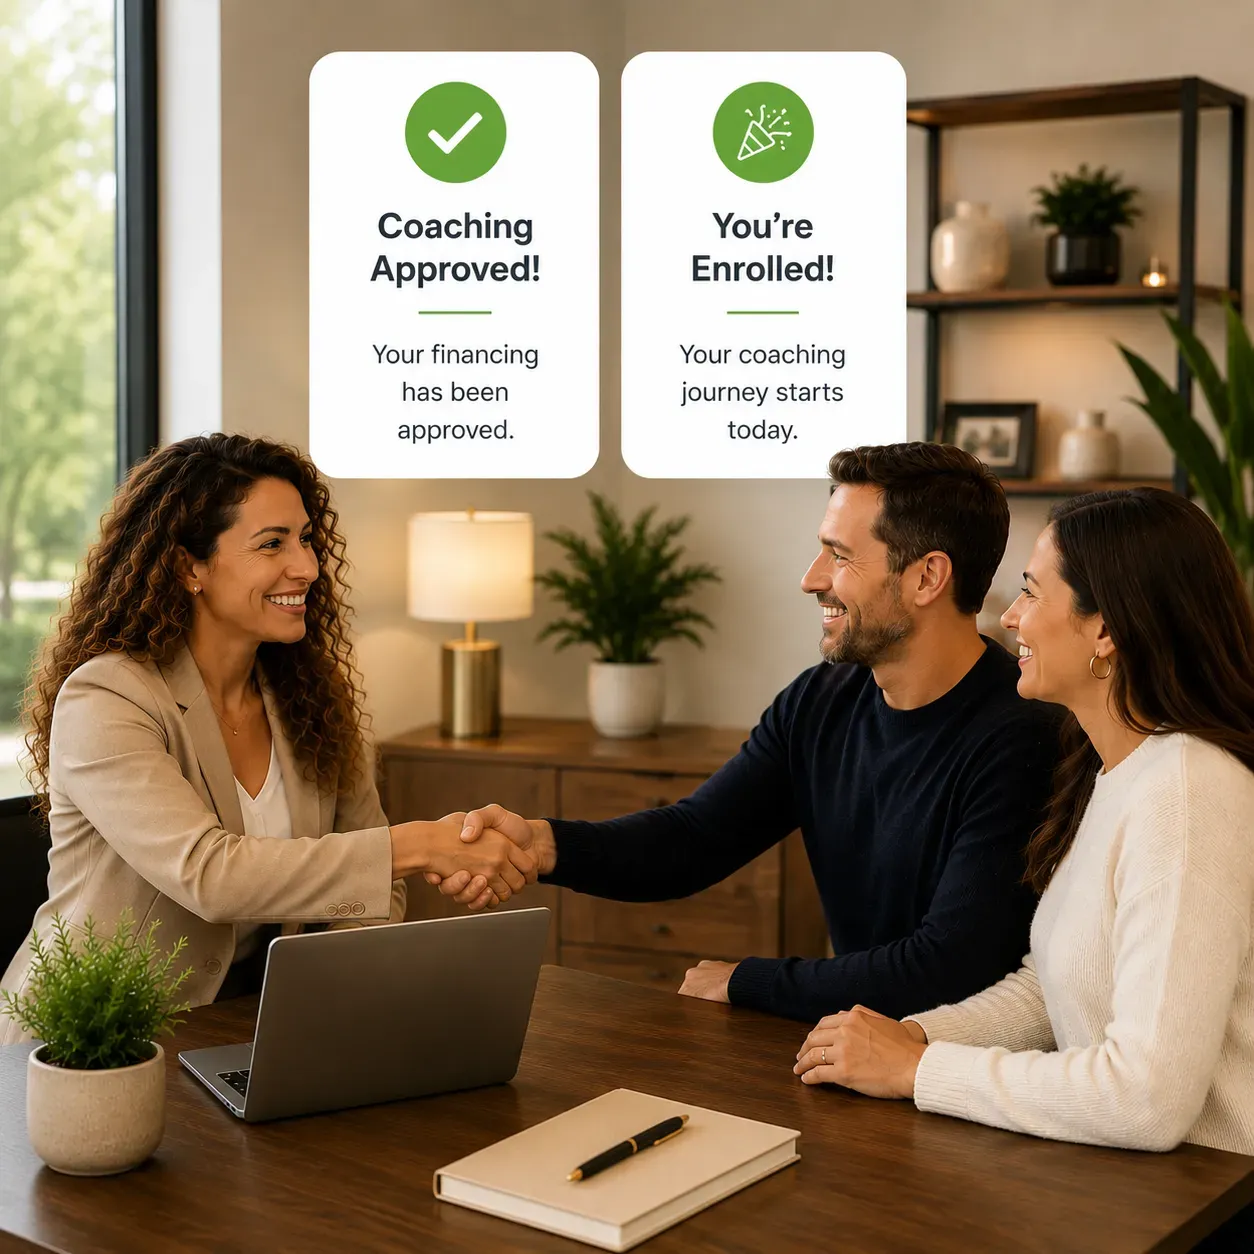
Offer coach financing to your clients.
Scale your high-ticket enrollments seamlessly. Let third-party lenders handle the underwriting and risk while you focus on coaching.
with multiple lending partners
direct to your bank account
(Prime, Near-Prime & Subprime)
amounts from $1,000 up to $50,000+
invoicing, or default risk
Start Offering Financing Today.
Help qualified clients compare payment options in minutes to complete enrollment faster.
- Turn hesitant prospects into committed clients.
- Flexible monthly payment options for your programs.
- Get paid upfront without carrying client payment default risk.